FTSE Posts Modest Gains as Energy and Mining Rebound Offsets Sticky Inflation Outlook
FTSE Posts Modest Gains as Energy and Mining Rebound Offsets Sticky Inflation Outlook
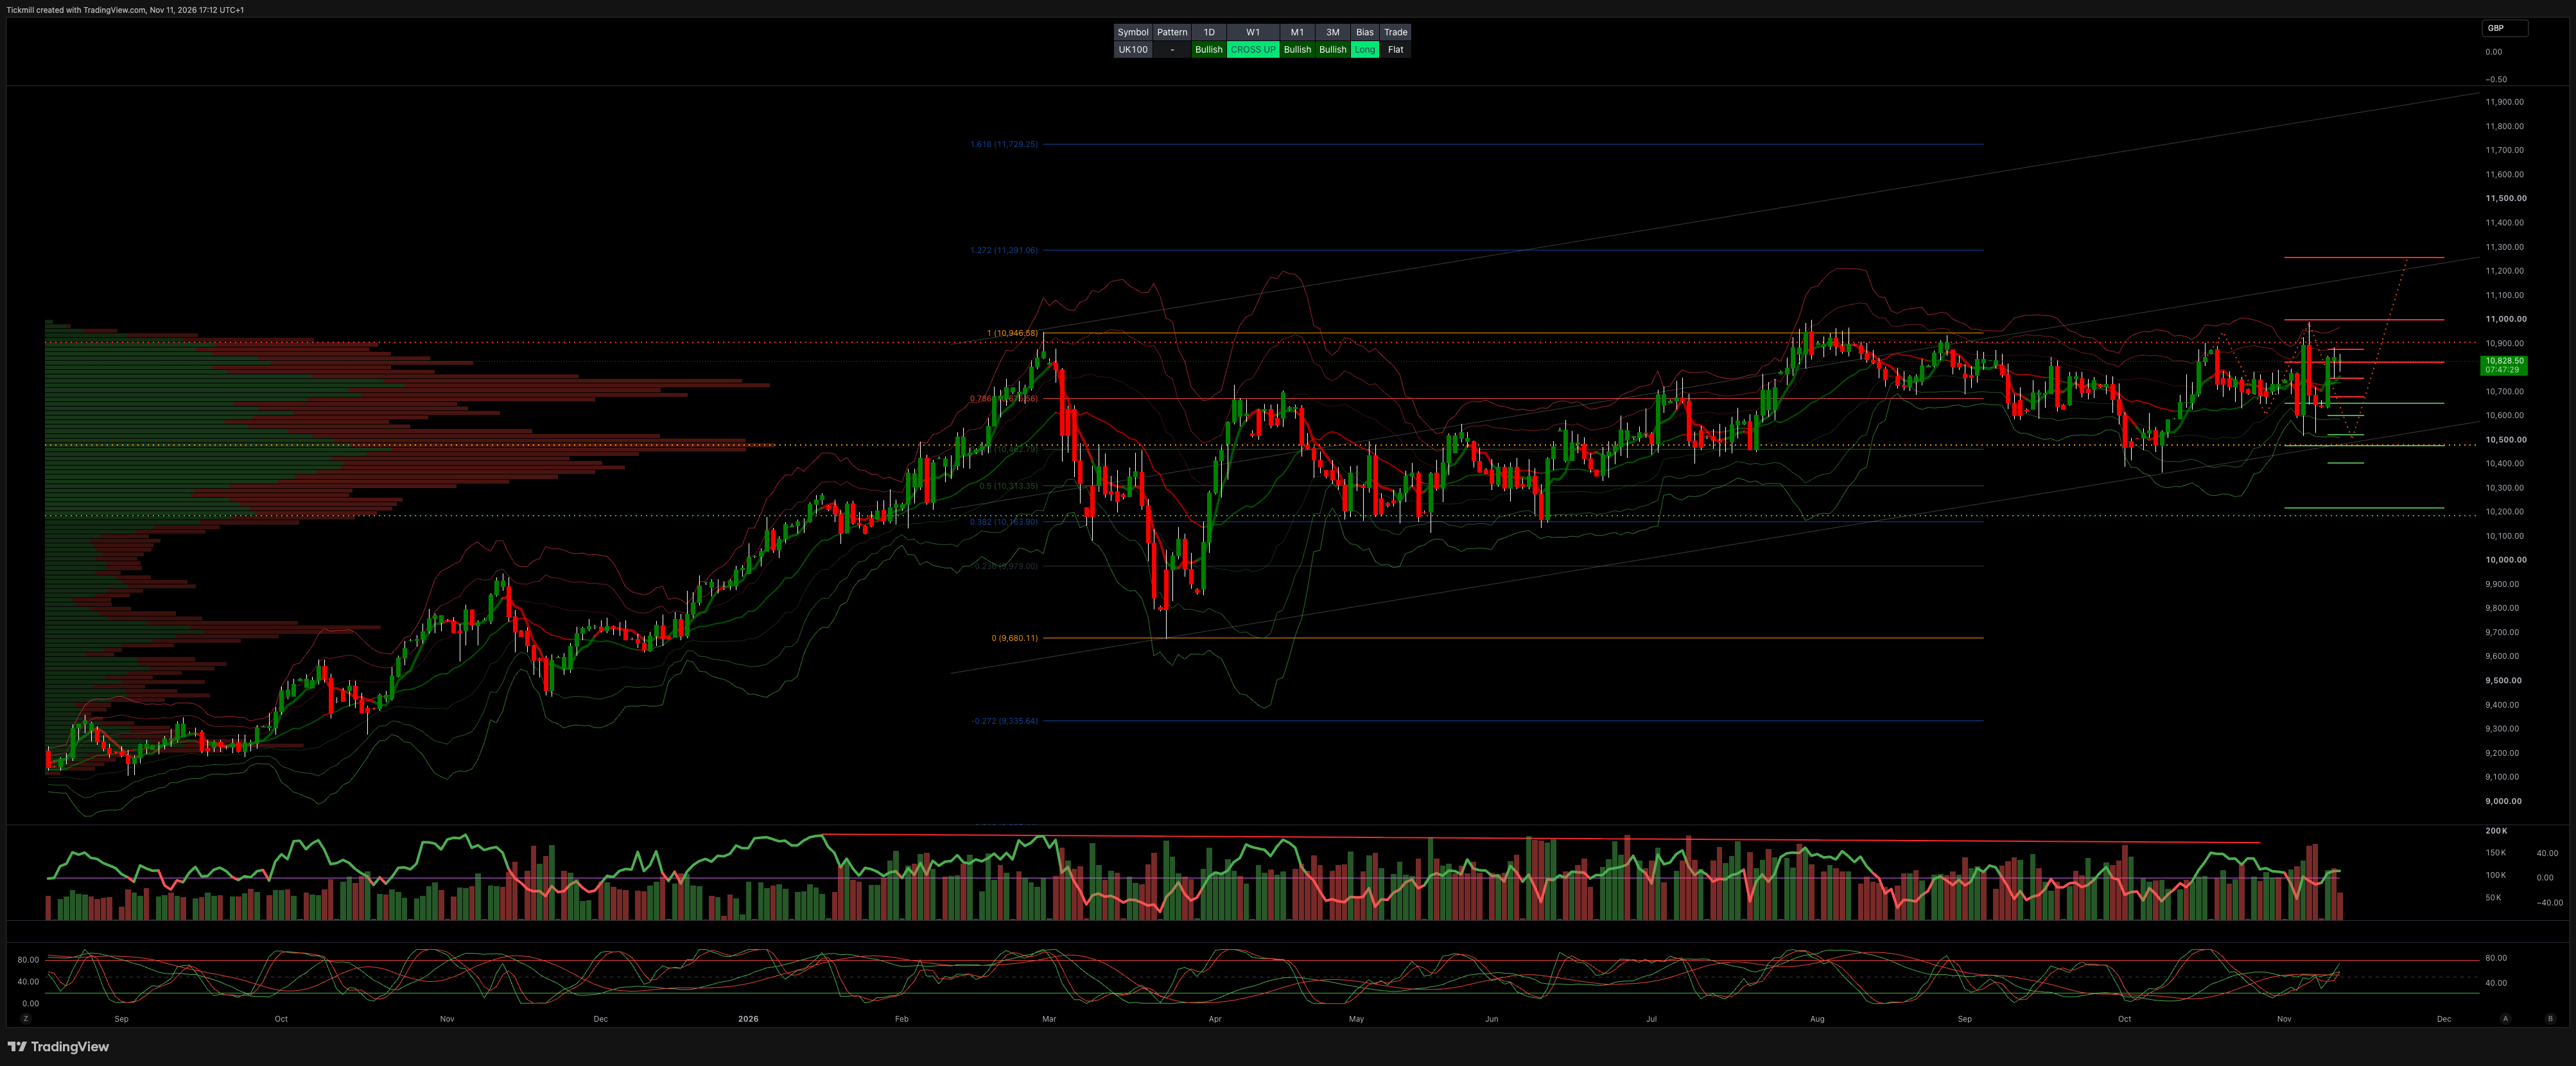
London's benchmark FTSE 100 posted modest gains on Wednesday, buoyed by a broad recovery across energy majors and mining heavyweights as crude oil and bullion prices staged a rebound. The advance snapped a multi-day slide for commodity producers, though upside momentum remained capped as market participants balanced fresh macroeconomic forecasts showing persistent inflation against caution ahead of Thursday's preliminary third-quarter GDP report.
Commodity-linked sectors and industrial engineering led the top flight. The energy sector jumped 1.9%, breaking a seven-session losing streak as crude rebounded from two-month lows; BP climbed 2.7% and Shell gained 1.6%. Industrial metal miners advanced nearly 2% alongside firmer copper prices, led by Anglo American, Antofagasta, and Glencore advancing between 2.3% and 2.6%. Precious metal miners added 1.8%, tracking a 0.4% uptick in spot gold. Engineering specialist Spirax Group surged up to 3.7% after confirming ten-month organic sales growth and adjusted operating margins aligned with consensus and ran ahead of first-half levels. Tech-focused Polar Capital Technology Trust added 2.9%.
Conversely, consumer discretionary and homebuilders acted as a drag on broader gains. The homebuilders index slipped 1.4% amid elevated mortgage rates and lingering affordability concerns, with JD Sports Fashion sliding 1.9% to lead blue-chip decliners, while defense contractor Babcock International dropped more than 1.7%. Outside the main index, broadcaster ITV tumbled 3.9% on the FTSE 250 after forecasting a fourth-quarter advertising revenue drop of as much as 10%.
Foreign exchange and fixed-income markets reflected transatlantic policy divergence. The six-currency U.S. Dollar Index climbed 0.44% to 102.68 on renewed bets of Federal Reserve rate hikes following Tuesday's hot U.S. CPI print. Consequently, GBP/USD dropped 0.32% to 1.3297, traversing a range of $1.3295 to $1.3356. EUR/GBP edged down 0.07% to 0.8360, while GBP/JPY ticked up 0.10% to 212.02. Defying the U.S. dollar's strength, sovereign bond yields across Europe eased; U.K. 10-year Gilt yields declined 0.51% to 5.2017% after fluctuating between 5.1833% and 5.2231% during the session.
On the domestic macroeconomic horizon, fresh forecasts from the National Institute of Economic and Social Research (NIESR) upgraded U.K. GDP growth projections for 2026, but warned that domestic inflation may not sustainably return to the Bank of England's 2% target until late 2030. Following the MPC's recent rate hike to 4.00%, LSEG pricing indicates money markets are now pricing in a 69% probability of another 25-basis-point increase at the December policy meeting.
Finish Line: London equities found solid ground as rebounding crude oil and metals prices lifted heavyweights Shell, BP, and Glencore, offsetting a drag from homebuilders. While softening Gilt yields provided modest relief, long-term inflation warnings from NIESR and rising December BoE rate hike bets keep market conviction guarded heading into Thursday's high-stakes Q3 GDP release.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!