Institutional Insights: Deutsche Bank Investor Flows & Positioning 9/11/26
DEUTSCHE BANK GLOBAL ASSET ALLOCATION BRIEFING: AFTER THE PLUNGE — TECH COILED SPRING & FORCED UNWIND
POSITIONING IMPLODES TO NEGATIVE EARNINGS PRICING WHILE INFLOWS SURGE
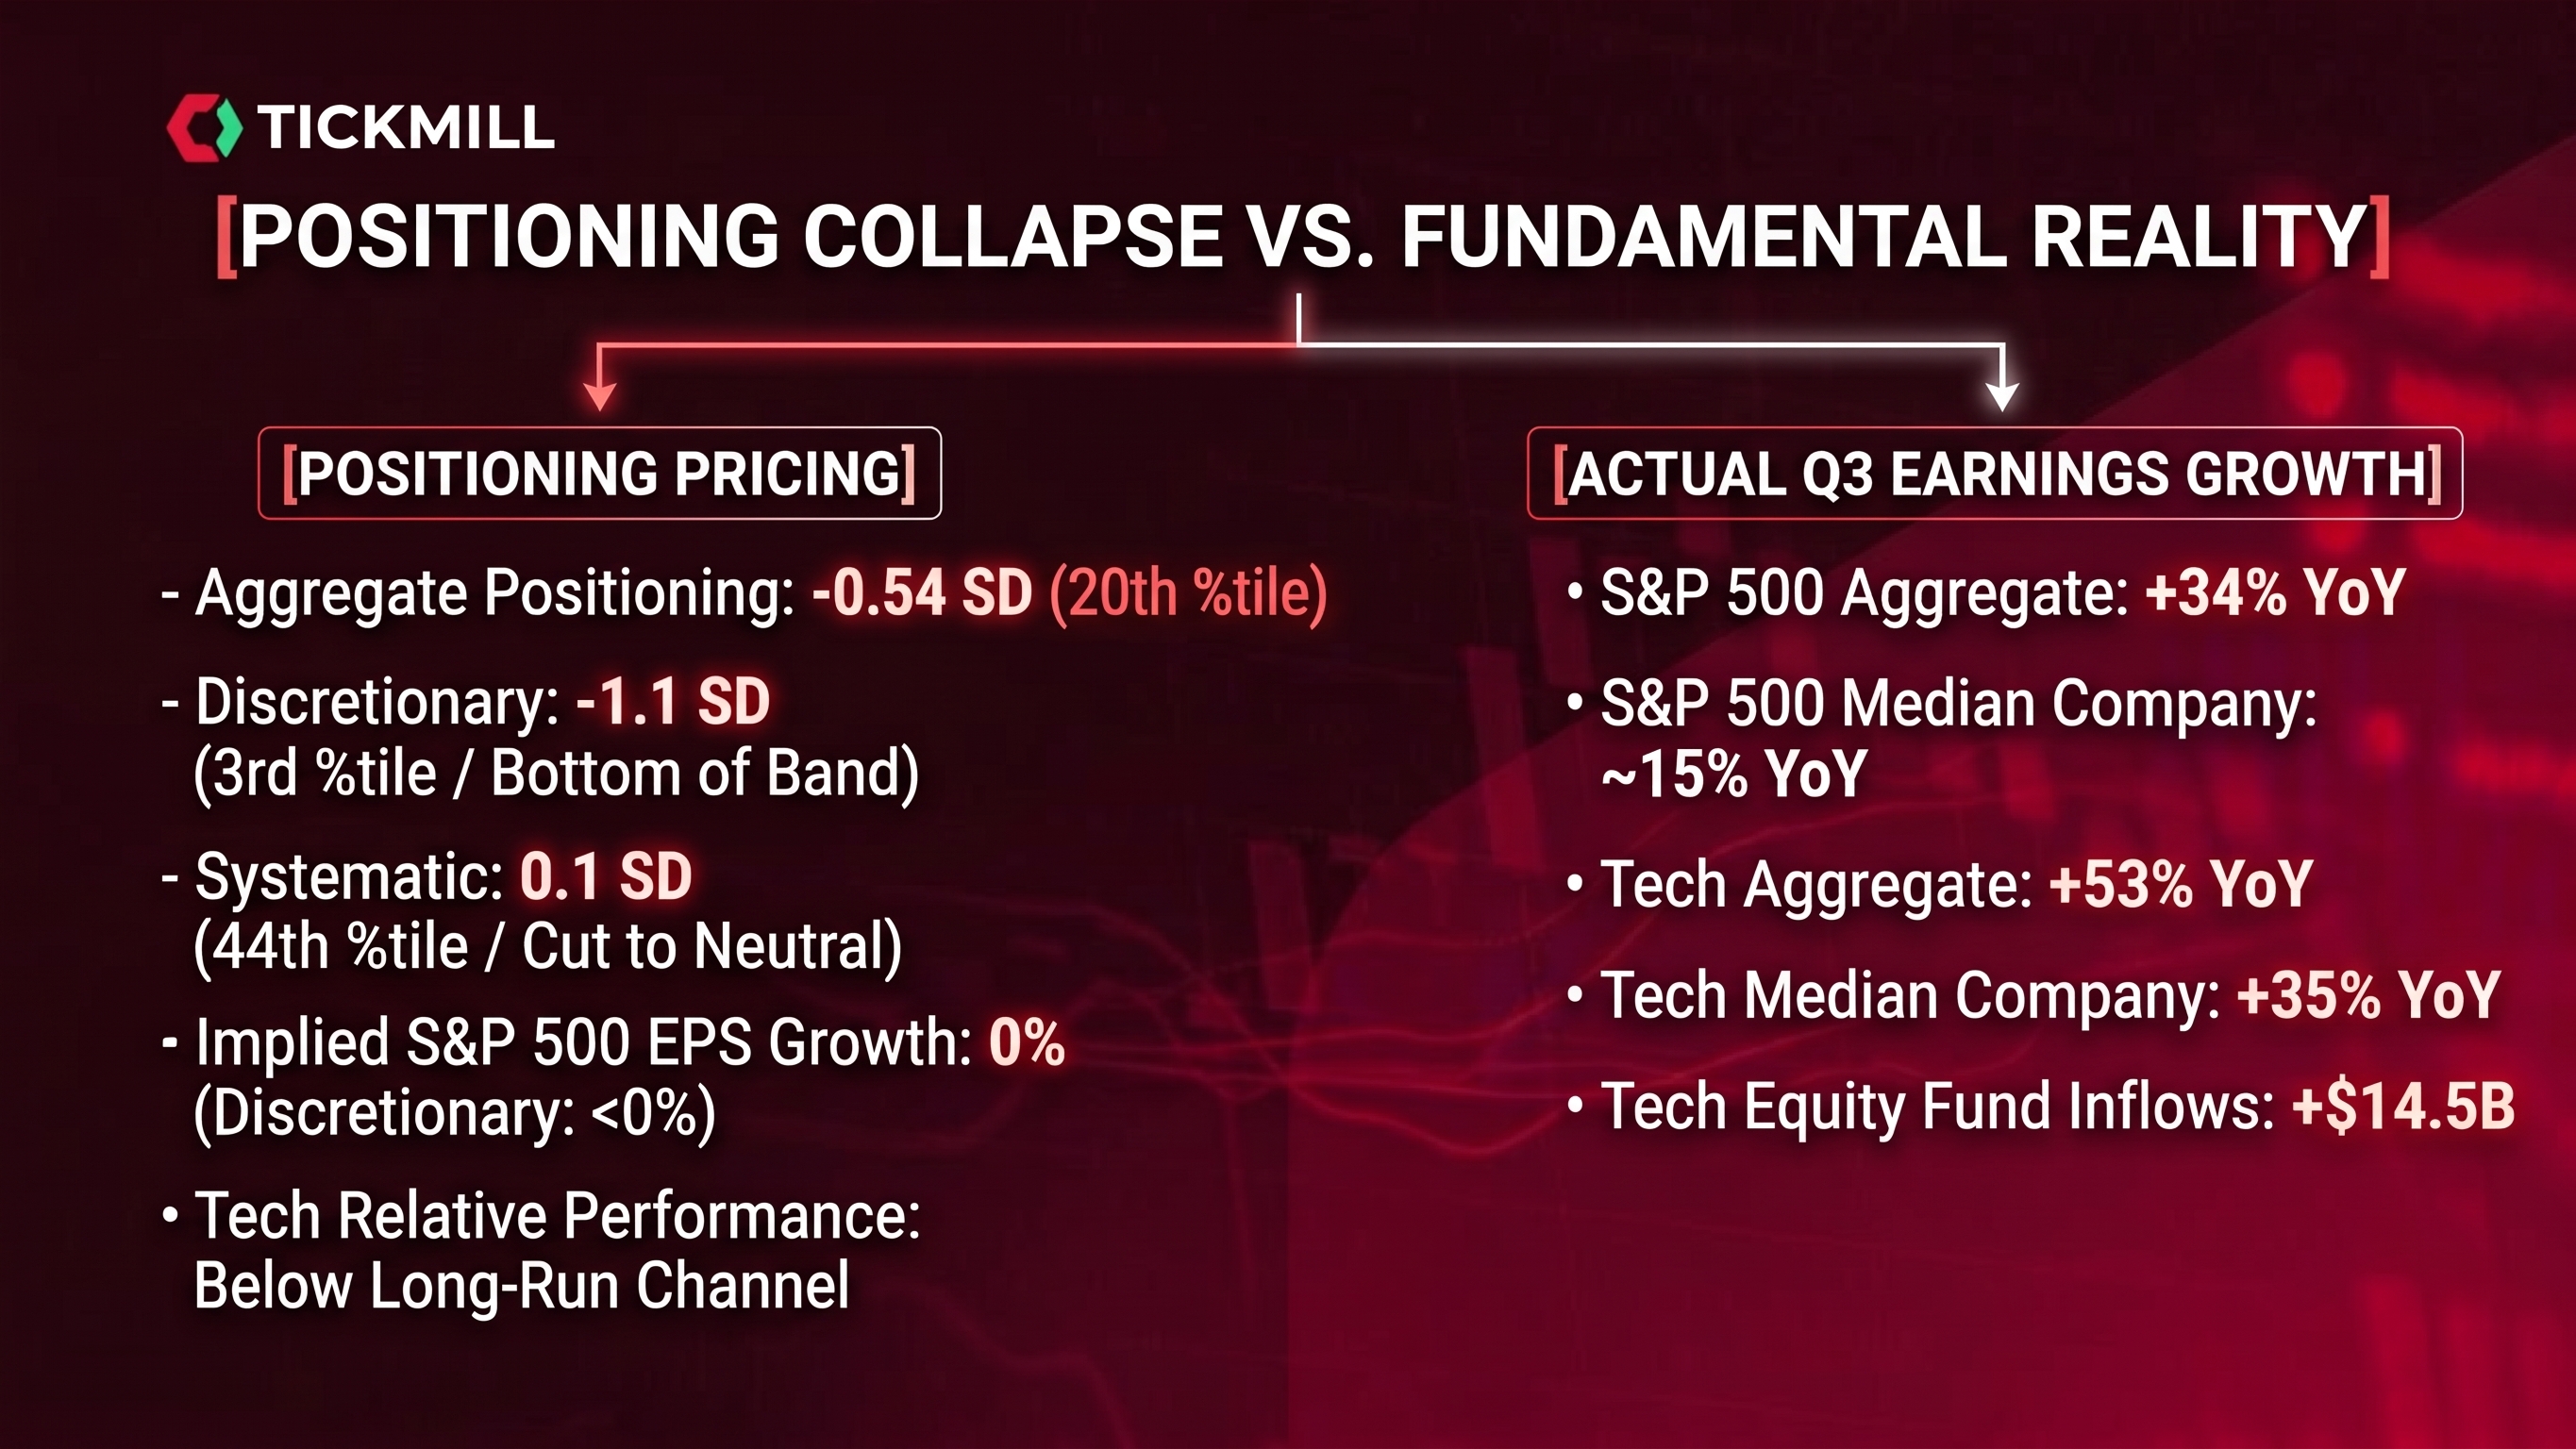
Deutsche Bank’s proprietary measure of equity positioning experienced one of the sharpest weekly collapses on record, plummeting into sizable underweight territory at -0.54 SD (20th percentile). The damage was led by discretionary investors, whose exposure collapsed to the absolute bottom of its historical channel at -1.1 SD (3rd percentile), while systematic strategies aggressively slashed exposure to neutral at 0.1 SD (44th percentile).
The divergence between positioning and underlying corporate fundamentals has reached historic extremes. Large-cap positioning now prices 0% earnings growth for the S&P 500, with discretionary positioning aligned with earnings turning negative. Similarly, the ratio of the S&P 500 to its 1-year moving average implies zero earnings growth. This stands in stark contrast to realized fundamentals: S&P 500 earnings expanded by +34% in both Q2 and Q3 2026, with the median index constituent delivering nearly +15% growth in Q3.
At the epicenter of the sell-off, Tech positioning plunged below the rest of the S&P 500 and broke below Liberation-day lows, fully pricing negative earnings growth. Yet aggregate Tech delivered +53% earnings growth in Q3 (+35% for the median tech company). Deutsche Bank argues the post-election crash was a mechanical, forced positioning unwind rather than an incremental macro shock, maintaining a high-conviction Overweight on Tech as risk-reward has become exceptionally asymmetric ("The Spring Is Coiled Again").
INVESTOR POSITIONING & VALUATION DISCONNECT
Positioning Breakdown:
Overall Equity Positioning: Dropped to -0.54 SD (20th percentile) in one of the steepest single-week drops on record.
Discretionary Managers: Plunged more than 1 SD below neutral to -1.1 SD (3rd percentile), anchoring at the lower bound of historical bands.
Systematic Strategies: Cut risk rapidly from elevated levels to neutral at 0.1 SD (44th percentile).
Pricing Zero/Negative Growth: The market multiple and moving-average ratios now fully discount a complete collapse in corporate profit expansion. Investors are treating the current earnings boom as narrow and unsustainable, despite median market breadth (+15% median S&P growth) reflecting solid underlying corporate health.
TECH SECTOR THESIS: "THE SPRING IS COILED AGAIN"
Positioning at Absolute Historical Floor: Tech positioning fell below the rest of the market and breached historical support shelves (falling beneath Liberation-day lows). Positioning is currently modeling negative forward earnings growth.
Relative Performance Channel Overshoot: Tech performance relative to the S&P 500 has broken modestly below its long-run secular trend channel—matching extreme historical overshoot anomalies seen during the onset of the Iran conflict and Liberation Day.
Election Reality Check: While post-election commentary blamed the Democratic sweep for the decline, DB highlights that the incremental policy news was modest. Political and local pushback against data-center power draw was widely acknowledged as a bipartisan issue long before the vote. The violent Thursday liquidation was primarily an unhedged, forced liquidation of crowded positioning.
Rating Stance: Reiterate Overweight Tech (upgraded from neutral on October 30; risk-reward viewed as even more attractive post-plunge).
GLOBAL FUND FLOWS: RECORD EM & TECH INFLOW SURGE ($89.2B TOTAL)
Despite catastrophic tape action on Thursday, institutional and retail capital deployed aggressive liquidity into equity funds:
Global Equity Fund Inflows: Surged to $89.2 billion this week—the highest weekly inflow in 20 weeks.
Emerging Markets (Record +$45.1B): Registered the largest weekly inflow on record, led overwhelmingly by China (+$34.5B) and Taiwan (+$8.6B).
United States Inflows: Solid institutional absorption of +$31.7 billion.
Tech Sector Absorption (+$14.5B): Technology equity funds captured +$14.5 billion in fresh net inflows, with institutional and retail buyers adding capital directly through Thursday's violent liquidation session.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!